 How Much Are They Worth?
Celebrity fortunes, explained
How did Ridley Scott build this fortune?
The answer unfolds through the career, earnings, deals and assets behind the headline estimate.
Before the fame
The background and early turning points that shaped Ridley Scott’s route to prominence.
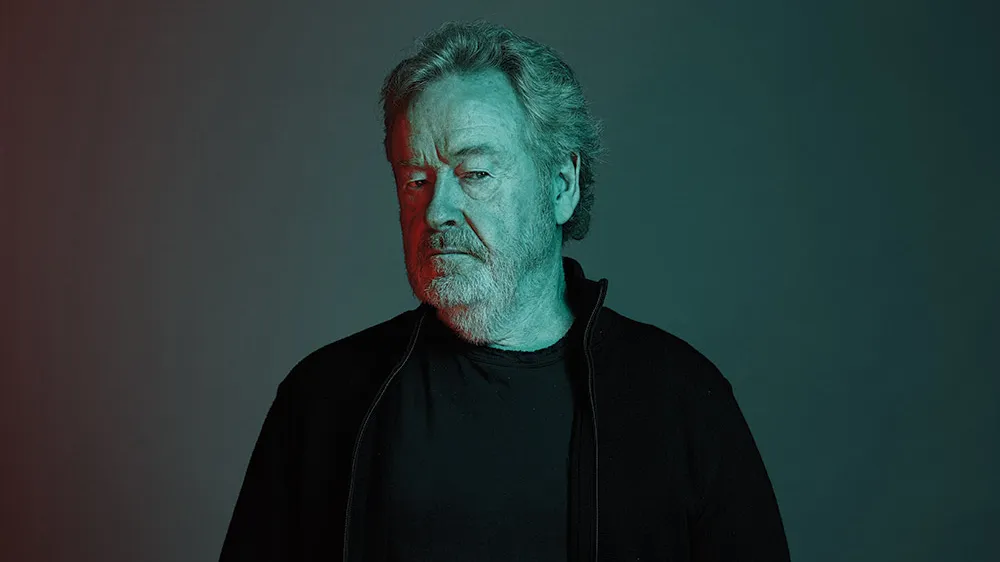
Scott was born in South Shields, England, in 1937 and studied at the Royal College of Art. He entered television through the BBC before moving into advertising, where short schedules and visual storytelling became a commercial training ground. In 1968 he and his brother Tony founded Ridley Scott Associates, now RSA Films. The Ridley Scott Creative Group’s company page describes RSA as a global commercials producer with offices in London, Amsterdam, Los Angeles, New York, Hong Kong and Greater China. That infrastructure is a business asset, not simply a director’s résumé line.
Scott’s debut feature, The Duellists, arrived in 1977, followed by Alien in 1979 and Blade Runner in 1982. Their long afterlives created franchise and catalogue associations, but underlying rights are divided among studios, writers and producers. HMW does not assume that Scott owns the Alien or Blade Runner libraries. His early advertising work, including the famous Apple “1984” commercial, is instead treated as the base of RSA’s operating history and as fee income earned over many campaigns.
The breakthrough years
The career decisions and defining moments that turned recognition into sustained earning power.
Alien established Scott as a major studio director, while Blade Runner eventually became a durable science-fiction property despite its difficult original release. Later films including Thelma & Louise, Gladiator and Black Hawk Down expanded his market across genres. The strongest public evidence of his personal quote is unusual because it concerns a job he rejected: Scott told The Guardian he turned down a $20 million fee to direct Terminator 3. It demonstrates negotiating power around 2003, but HMW records zero income from that offer and does not apply the same fee to every film.
What the work can earn
Reported pay, contracts, royalties and performance income reveal how the fortune was funded.
Scott’s modern output confirms that his commercial relevance survived for decades. The Martian grossed about $630 million worldwide, while Gladiator II produced another large theatrical run. Box Office Mojo records $462,180,717 worldwide for Gladiator II. Those receipts first flow to exhibitors and distributors and must recover production, marketing and financing costs; Scott receives only contracted directing, producing and possible participation payments. The entire box office therefore contributes zero directly to the estimate.
Directing fees are the clearest personal source. The declined $20 million offer supplies a high-end historical benchmark, not an average. HMW models lower real fees on smaller or less commercial projects and recognises that some compensation may be routed through loan-out entities. Producer fees and contingent participation can add to the return when Scott Free is involved, but profitability varies and even a large gross can disappoint after cost. The model therefore counts contracted work across more than four decades, not a percentage of combined cinema ticket sales.
The business beyond the main career
Endorsements, ownership interests and investments can keep compounding long after the initial breakthrough.
RSA adds advertising and branded-content economics distinct from feature directing. Its official page lists clients including Adidas, Apple, BBC, Louis Vuitton, Microsoft, Pepsi, Puma, Toyota and Vodafone, while RSA’s director roster means revenue does not depend solely on Scott personally shooting commercials. A company collects production fees but also pays directors, producers, crews, offices, insurance and development expense. HMW includes a conservative value for Scott’s ownership interest and distributions; it does not treat client billings as his income.
Scott Free Productions is the other major asset. The group describes it as Scott’s film and television production vehicle and reports more than 100 Emmy and 60 Academy Award nominations across its projects. In 2020, Deadline reported a multiyear first-look television agreement with Apple, under which Scott Free would develop global projects for Apple TV+. Contract value was not disclosed. Because Scott Free is private and no arm’s-length sale or financing valuation has been published, HMW values its probable earnings capacity conservatively rather than inventing a venture-style multiple.
Notable luxury item
A reported property or major asset offers a tangible glimpse of the wealth behind the public estimate.
Property sales show that Scott accumulated material real estate, though former homes are not current assets. The Standard reported that he sold Old Grove House in Hampstead privately for £26.5 million in 2013 after living there for more than fifteen years. Purchase price, refurbishment cost, tax and debt were not disclosed, so only net proceeds after large allowances enter the historical savings model. In California, Realtor.com reported a Malibu land purchase for $7.2 million and sale for $11 million two years later. A separate former Malibu home was sold by Scott in 2006 for roughly $11.5 million, inferred from the Los Angeles Times’ later $9.5 million sale report. HMW does not count any of these sold properties again as present holdings.
Ridley Scott’s estimated net worth
Public estimates vary because private contracts, investments, taxes and liabilities are not fully disclosed.
How this estimate is calculated
HMW models roughly five decades of advertising, directing and producing cash flow. It uses the rejected $20 million offer only as evidence that Scott reached an elite quote, applies much lower assumed compensation across most films, and adds restrained producer fees and participation where Scott Free credits support them. It then assigns private-company value to RSA and Scott Free based on longevity, global offices, first-look relationships and recurring output, but applies a heavy discount because revenue, profit, debt and minority interests are unknown. Documented Hampstead and Malibu proceeds enter after estimated transaction costs, refurbishment, debt and tax, while sold homes are not treated as current assets. Corporate overhead, project development losses, agents, managers, legal and accounting costs, UK and US taxation, family transfers and personal spending are deducted. The result is rounded substantially because company ownership is the largest unknown.
Scott’s name helps package expensive films, recruit actors and support financing. His continuing workload is unusually extensive for a director in his eighties, encompassing Napoleon, Gladiator II, The Dog Stars and producing work across film and television. Fandango’s title-by-title credits distinguishes his director, producer and executive-producer roles on recent projects. Those credits indicate multiple payment streams, although they do not reveal fees or backend terms.
The reliable evidence establishes an accepted $20 million directing offer, valuable property exits, ownership of operating production businesses and a continuing stream of director and producer credits. It does not disclose Scott’s actual film contracts, backend participation, RSA profit, Scott Free ownership arrangements after Tony Scott’s death, corporate debt, trusts or current real estate. Even the $462.2 million Gladiator II gross says nothing precise about Scott’s participation. The estimate excludes online celebrity lists, assigns no standalone value to awards or reputation and avoids counting the same project as directing income, producer income and box-office income.