 How Much Are They Worth?
Celebrity fortunes, explained
How did Jordan Spieth build this fortune?
The answer unfolds through the career, earnings, deals and assets behind the headline estimate.
Before the fame
The background and early turning points that shaped Jordan Spieth’s route to prominence.
Jordan Spieth is a three-time major champion and former world number one. That distinction matters financially because the subject’s earning history is tied to identifiable events, rights and businesses rather than a generic assumption about what a successful golf figure should be worth. This profile treats reported compensation as evidence, not as cash automatically retained.
Spieth turned professional after a standout University of Texas period and won on the PGA Tour as a 19-year-old, accelerating both prize income and sponsor demand.
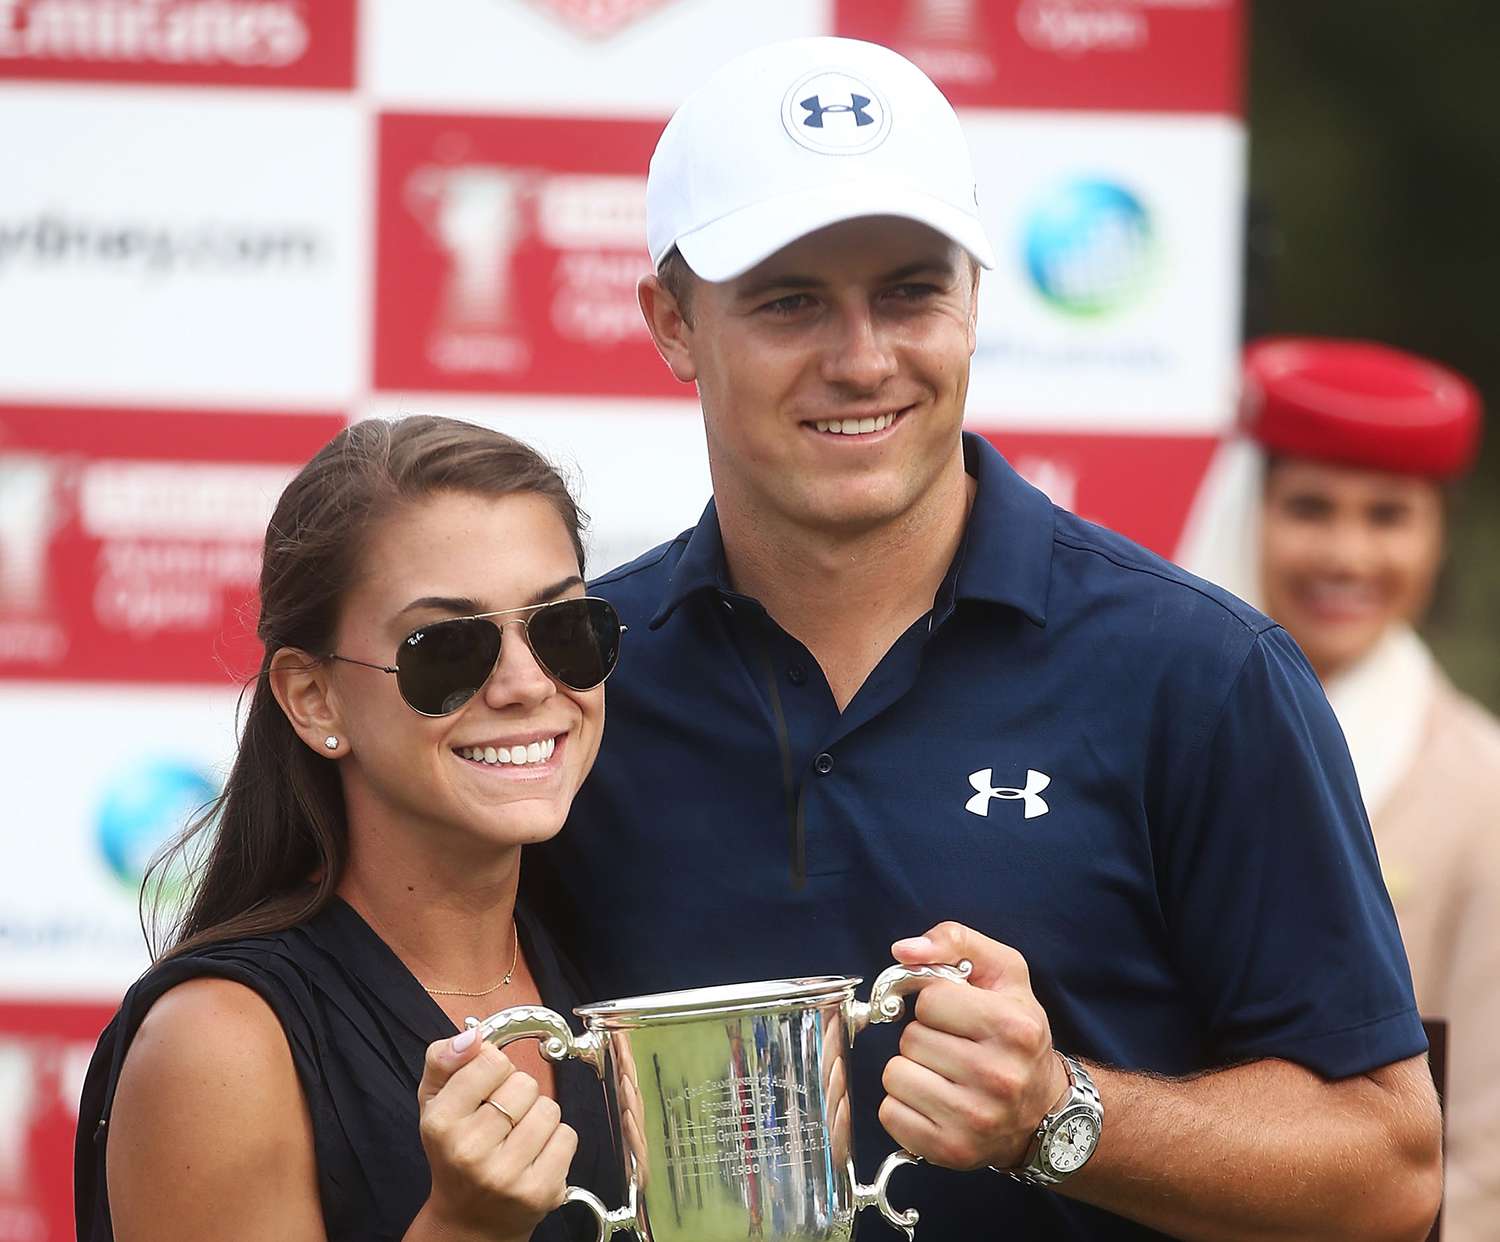
Spieth won two U.S. Junior Amateurs, played at the University of Texas and turned professional in 2012 without a full Tour card. His first PGA Tour victory at the 2013 John Deere Classic created immediate eligibility and sponsor value. The Masters’ account of his 2015 win records the season that transformed his economics: he won at Augusta and the U.S. Open before adding the 2017 Open Championship. HMW counts the actual purses and subsequent commercial years, not a dollar value for junior or college honors.
The breakthrough years
The career decisions and defining moments that turned recognition into sustained earning power.
The decisive professional breakthrough was his breakthrough 2015 Masters and U.S. Open season. It expanded audience, negotiating leverage and access to premium events. A breakthrough can create future earning capacity, but the estimate does not capitalize fame by itself; only documented compensation, durable rights and identifiable commercial activity are given financial weight.
The PGA Tour career table records about $68.6 million of official prize money, excluding FedEx bonuses and endorsements.
What the work can earn
Reported pay, contracts, royalties and performance income reveal how the fortune was funded.
Major milestones include the 2017 Open Championship and a long run as a leading sponsor athlete. The sequence is important because title bouts, major wins and headline events typically carry higher direct compensation and stronger sponsorship value. Career records also prevent double-counting widely repeated purse or prize reports that refer to the same event. Not every milestone receives a separate dollar value: several are used only to confirm the period in which income and commercial leverage peaked.
His results after the 2015 peak have fluctuated, so this estimate does not project the commercial economics of that exceptional season forever.
The principal income channels were tour winnings, FedEx bonuses, endorsements and course-related investments. Public prize, purse or compensation reports are gross figures. They precede promoter or tour deductions, management, coaching and training costs, travel, taxes and personal spending, so the calculation applies substantial retention discounts rather than simply adding headlines.
Forbes’ athlete profile has repeatedly identified Spieth’s major sponsors and annual earnings; those estimates are used as gross-year evidence, not a personal balance sheet.
The business beyond the main career
Endorsements, ownership interests and investments can keep compounding long after the initial breakthrough.
Spieth’s commercial foundation is the long Under Armour relationship, supplemented over time by AT&T, Rolex and other sponsors. Forbes’ athlete profile supplies annual gross estimates and sponsor context, while Under Armour’s extension confirms that the apparel relationship continued beyond its initial term. HMW carries endorsement income through supported seasons, reduces it for agency and tax, and avoids treating product or performance incentives as guaranteed cash. Donations and grants administered by the Jordan Spieth Family Foundation are excluded entirely from his assets.
Business interests include strong endorsement evidence supports the estimate, though private portfolio values are unavailable. Where a private company has no audited accounts or transaction price, this profile does not assign it an aggressive speculative valuation. It recognizes only a restrained contribution consistent with the public evidence and separates operating-brand visibility from money owned personally.
Real estate, tax residency, investment allocations and endorsement incentives are not fully disclosed; official money also arrives before caddie percentages and travel costs.
Notable luxury item
A reported property or major asset offers a tangible glimpse of the wealth behind the public estimate.
Spieth’s public records do not disclose current mortgages, securities, sponsor bonuses or the economics of any course-related investments. His earnings also arrived unevenly: the 2015 peak, FedEx bonuses and later seasons should not be smoothed into a permanent annual rate. HMW models investment growth on retained cash from those specific years, includes a normal housing and consumption allowance, and assigns no personal value to foundation accounts. Undisclosed real estate is not priced from entertainment-site claims.
Jordan Spieth’s estimated net worth
Public estimates vary because private contracts, investments, taxes and liabilities are not fully disclosed.
How this estimate is calculated
Spieth’s estimate begins with about $68.6 million in PGA Tour official money. FedEx and other reported bonuses are added only when outside that table, and Forbes year totals are split between golf and endorsements so neither component is repeated. Playing income loses caddie percentages, travel, coaching and management; sponsor income loses representation costs; both receive a blended federal and state tax reserve. HMW then compounds retained capital conservatively from the actual high-income seasons and subtracts household spending. It continues a reduced Under Armour and sponsor contribution through August 2026, places no value on future renewals or foundation assets, and uses no guessed private-company multiple.
Jordan Spieth developed a public profile extending beyond results. Major media and governing-body coverage shows sustained audience interest and a recognisable international brand. Reach can support licensing, appearances and sponsorship, although follower counts and publicity are not treated as personal assets without evidence of monetisation.
Under Armour’s 2022 announcement extended a relationship begun in 2013, unusually concrete evidence of a long-duration endorsement even though financial terms remain private.
PGA Tour official money gives a reliable tournament floor, the Masters and Open records fix his major timeline, Under Armour verifies contract continuity, and Forbes supplies non-audited annual earnings estimates. FedEx and other bonus pools can sit outside official money and inside Forbes totals, so HMW reconciles them by season. Private tax returns, caddie arrangements, investment performance and sponsor incentive clauses are unavailable. The model therefore treats endorsements as variable income tied to documented competitive periods rather than a perpetual annuity.